Loan Officer Resume: Examples (2026)

Loan officer resume example with summaries, bullets, skills, mortgage licensing guidance, official pay figures and a free Classic template.

Template:

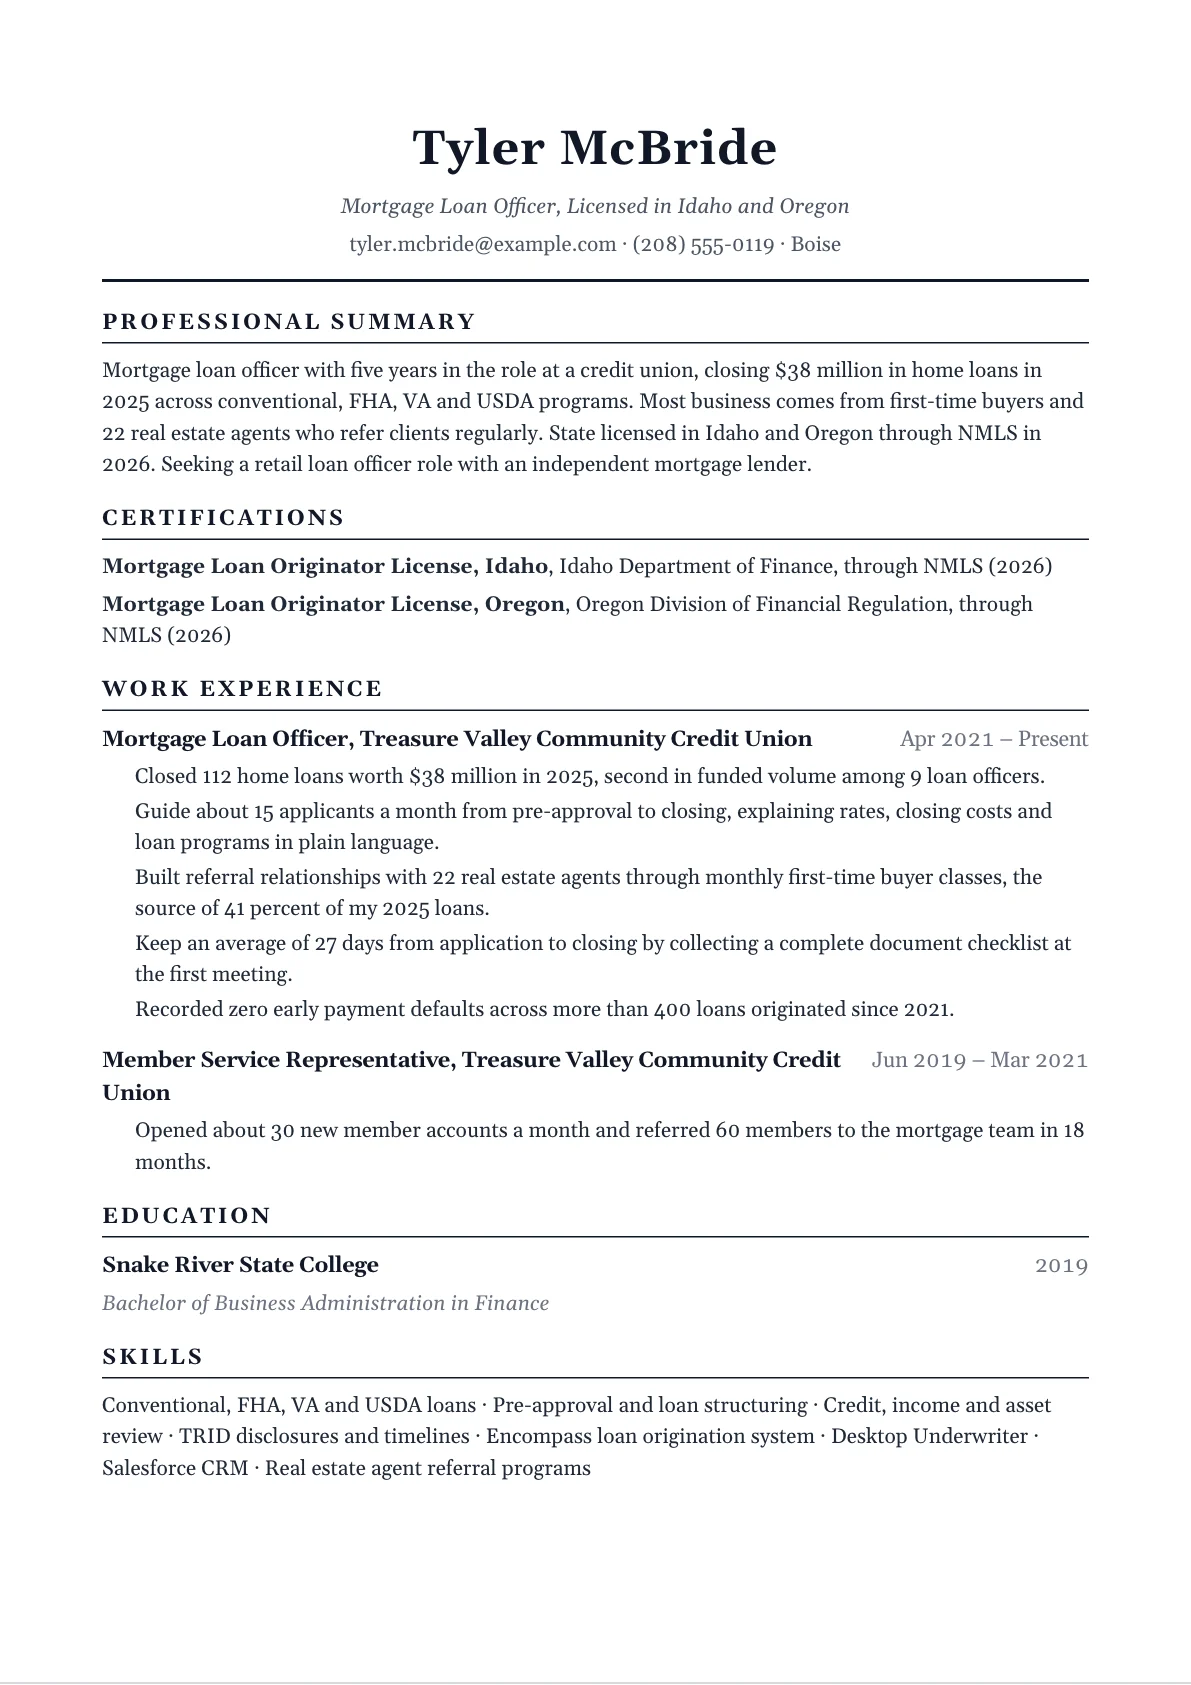
Fictional example: a credit union mortgage loan officer with five years in the role, newly state licensed, applying for a retail loan officer job at an independent mortgage lender. Names and career details in the samples are invented for illustration.

Why this resume works

  • Tyler's fictional 2025 record separates one hundred twelve funded loans and thirty-eight million dollars from his rank among nine originators. Funded principal is not revenue or profit.
  • Idaho and Oregon license entries identify the claimed jurisdictions and award year. Actual current status and employer-linked authorization still need verification.
  • Referral activity and the closing process explain different parts of the work. A past referral share does not guarantee that relationships or borrowers transfer to another employer.
Edit & download this resume

Create a free account to edit this example and download a PDF with no watermark. Classic is free; Compact, Creative, and Bold require a Job Search Pass.

A loan officer resume should identify the kind of lending, your actual borrower or credit work and the authorization relevant to the role. Explain production and process using clear units, while separating origination, underwriting decisions and funded outcomes.

This guide follows fictional mortgage officer Tyler McBride from a credit union toward an independent lender. Use the selectable sample, lending choices and worked production revision below. Check the employer, activities, jurisdiction and current record instead of treating a generic NMLS entry as permission to originate.

Loan officer resume example: text version

This is the fictional example shown above in selectable text. Use its structure, then replace every sample detail with your own. The image and editable example use the same resume data.

Tyler McBride

Mortgage Loan Officer, Licensed in Idaho and Oregon

tyler.mcbride@example.com

(208) 555-0119

Boise, ID, US

Summary

Mortgage loan officer with five years in the role at a credit union, closing $38 million in home loans in 2025 across conventional, FHA, VA and USDA programs. Most business comes from first-time buyers and 22 real estate agents who refer clients regularly. State licensed in Idaho and Oregon through NMLS in 2026. Seeking a retail loan officer role with an independent mortgage lender.

Training and certificates

Mortgage Loan Originator License, Idaho

Idaho Department of Finance, through NMLS

2026

Mortgage Loan Originator License, Oregon

Oregon Division of Financial Regulation, through NMLS

2026

Experience

Mortgage Loan Officer

Treasure Valley Community Credit Union

From: Apr 2021

To: Present

  • Closed 112 home loans worth $38 million in 2025, second in funded volume among 9 loan officers.
  • Guide about 15 applicants a month from pre-approval to closing, explaining rates, closing costs and loan programs in plain language.
  • Built referral relationships with 22 real estate agents through monthly first-time buyer classes, the source of 41 percent of my 2025 loans.
  • Keep an average of 27 days from application to closing by collecting a complete document checklist at the first meeting.
  • Recorded zero early payment defaults across more than 400 loans originated since 2021.

Member Service Representative

Treasure Valley Community Credit Union

From: Jun 2019

To: Mar 2021

  • Opened about 30 new member accounts a month and referred 60 members to the mortgage team in 18 months.

Education

Bachelor of Business Administration in Finance

Snake River State College

To: 2019

Skills

Conventional, FHA, VA and USDA loans

Pre-approval and loan structuring

Credit, income and asset review

TRID disclosures and timelines

Encompass loan origination system

Desktop Underwriter

Salesforce CRM

Real estate agent referral programs

Choose mortgage, commercial or consumer lending evidence

  • Mortgage origination: actual programs, funded production, borrower communication and verified authorization.
  • Commercial lending: actual relationship or portfolio work, credit analysis and delegated recommendations or decisions.
  • Consumer lending: actual products, service, application review and responsibility within the institution.
  • Moving from processing: real file and communication work plus accurate licensing progress. Do not claim originator duties you were not authorized to perform.

Worked production revision

Overstated: Generated thirty-eight million dollars in profit and can transfer every referral to a new lender.

Supported by the fictional sample: Closed one hundred twelve home loans worth thirty-eight million dollars in 2025, second in funded volume among nine loan officers.

For your own measure, define loan count, principal, period and stage. For pull-through or default claims, explain the eligible population and observation window. Faster closing alone does not establish compliance or sound underwriting.

Replace Tyler's invented record in free Classic, save with Update and inspect the PDF for current status, dates, actual authority and confidentiality. Confirm employment-linked authorization before presenting yourself as ready to originate for a different lender.

Loan officer pay and job outlook

Official figures for Loan Officers.

Median pay (2025)
$76,690 per year ($36.87 per hour)
Jobs in 2025
283,000
Job outlook, 2025 to 2035
1%, slower than average
Change in jobs, 2025 to 2035
+3,100
Typical entry-level education
Bachelor's degree
Work experience needed
Less than 5 years
On-the-job training
Moderate-term on-the-job training

Sources: U.S. Bureau of Labor Statistics, Occupational Outlook Handbook: Loan Officers, checked September 2026; O*NET OnLine: Loan Officers, checked September 2026.

How to write a loan officer resume

1

Identify the lending role

Name mortgage, consumer, commercial or other actual lending experience. Explain relevant duties and actual approval authority rather than treating every role as the same.

2

Make authorization precise

State the actual jurisdiction, license or registration and current status relevant to your duties. Verify employer-linked requirements and applicable exceptions with the regulator and employer.

3

Define production and the period

Separate applications, locks, closings, funded loan count and principal. Report commissions or revenue only when separately documented and permitted.

4

Explain the borrower and credit process

Describe discovery, document review, program discussion, conditions and coordination within actual authority. Do not imply you independently approved every application.

5

Use relevant systems and evidence

Name actual origination, credit, pricing and relationship tools with their tasks. Protect borrower and confidential partner information.

6

Check the application and PDF

List actual education and training separately from authorization, follow requested length/file rules and inspect dates, units and credential status in the PDF.

Skills and keywords for a loan officer resume

These are the skills lenders mention most in loan officer postings. Use the ones that are true for you, in the posting's words, and prove the main ones in your bullets.

Hard skills

  • Loan origination and pre-approval
  • Credit report, income and asset analysis
  • Debt-to-income and loan-to-value calculations
  • Conventional, FHA, VA and USDA guidelines
  • Loan disclosures and closing timelines
  • Rate locks and pricing
  • Refinance and home equity analysis
  • Commercial or small business credit analysis
  • Pipeline management
  • Referral partner development

Soft skills

  • Explaining loan terms to first-time borrowers
  • Building relationships with agents and builders
  • Staying organized with many files at once
  • Delivering bad news clearly and kindly
  • Honesty under sales pressure
  • Following through until closing day

Tools and software

  • Encompass, Byte or Calyx loan origination systems
  • Blend or other digital application portals
  • Fannie Mae Desktop Underwriter
  • Freddie Mac Loan Product Advisor
  • Optimal Blue or other pricing engines
  • Salesforce, Jungo or Total Expert CRM

Loan officer resume summary examples

These summaries are separate fictional illustrations, not additional facts about Tyler. Replace lending, qualifications, responsibility and results with your own record.

New or junior loan officer

Former loan processor with two years preparing about 25 mortgage files a month for underwriting, now licensed as a mortgage loan originator in Texas. Know conventional and FHA guidelines, disclosures and the document checklist from the processing side. Seeking a junior loan officer or loan officer assistant role on a high-volume retail team.

Experienced mortgage loan officer

Retail mortgage loan officer with seven years at a national lender, averaging $52 million in funded volume a year and consistently in the top 10 percent of the region. Strong with self-employed borrowers and VA loans. Licensed in 3 states; seeking a senior loan officer seat with a purchase-focused lender.

Commercial or senior lender

Commercial loan officer with eleven years at a regional bank, managing a portfolio of 85 business relationships and $140 million in loans with no charge-offs in the last four years. Structure owner-occupied real estate, equipment and SBA loans. Seeking a senior commercial lender or team lead role.

Loan officer resume bullet examples

These bullets are separate fictional illustrations. Replace every task and figure with your own supported work, actual authority and permitted evidence.

  • Funded $46 million across 150 purchase and refinance loans in 2025, 118 percent of annual goal.
  • Grew referrals from local home builders from 2 to 7 partners in one year by hosting on-site buyer events.
  • Cut average time from application to clear-to-close from 34 to 24 days by pre-reviewing income documents.
  • Originated 40 VA loans in a year after completing lender training on VA guidelines and appraisals.
  • Held a 98 percent pull-through rate from rate lock to closing over 12 months.
  • Answered about 60 online leads a week within 15 minutes, converting 11 percent to applications.
  • Restructured 18 declined applications into approvable loans by adjusting down payment or loan program.
  • Managed a pipeline of 35 active files with weekly updates to each borrower and agent.
  • Built a Spanish-language first-time buyer seminar that produced 26 closed loans in its first year.
  • Reviewed financial statements and tax returns for 60 small business applicants a year for lines of credit up to $500,000.
  • Mentored 3 new loan officers through their first 90 days, with each closing loans in month two.

Licensing for mortgage loan officers

For residential mortgage work, report the actual state license, federal registration or other applicable status accurately. The CFPB state-licensing rule depends on activities and contains exceptions, while covered-institution registration rules address subject employees. Do not decide authorization from job title alone.

  • Idaho Department of Finance provides MLO licensing requirements and applicable depository-employment exemptions. Use the actual regulator record and role requirements.
  • Oregon DFR distinguishes license approval, accepted employer sponsorship and inactive status, with a separate eligible temporary-authority exception. An award year alone does not show active authority for a new employer.
  • List actual credential, jurisdiction and current status, and a real NMLS identifier when appropriate. Tyler's invented sample omits an identifier to avoid assigning another person's record.
  • Training, a passed test and an application are different from an issued or active license. Check the responsible regulator and employer for your actual activities rather than applying mortgage rules to every lending role.

The example, line by line

Tyler is fictional and targets mortgage lending. One hundred twelve funded loans total thirty-eight million dollars in 2025, with second place among nine originators by funded volume. That is loan principal, not commissions, profit or total company revenue.

Twenty-two agent relationships and first-time-buyer classes are associated with forty-one percent of his 2025 loans. The record does not supply a transferable book of clients or permission to bring contacts to another employer. Protect borrower and partner information.

Fifteen monthly applicants, twenty-seven average days to closing and more than four hundred loans since 2021 use different periods and populations. The early-default statement supplies no definition or observation window, so do not turn it into a guaranteed lifetime credit outcome.

The two 2026 state-license entries are fictional qualification details. They do not verify active sponsorship or authorization at a new employer. The current role and member-services role remain separate; sixty referrals over eighteen months are not sixty loans closed.

Mistakes that cost loan officers interviews

  • Calling funded principal revenue or profit changes the production measure.
  • Describing a test pass, NMLS identifier or inactive record as active origination authority can misstate qualification.
  • Claiming credit approval or policy exceptions you did not control exaggerates responsibility.
  • Promising a new employer every past referral or borrower relationship assumes portability and permissions the record does not establish.
  • Using an undefined default or pull-through rate can hide its actual period and eligible population.

Other finance and sales resume examples close to this one:

Every example is in the resume examples hub, grouped by job and situation.

Build it free, no watermark

Create a free CVPoet account before editing. Start from this example in the free Classic template or start a blank page, and download a PDF with no watermark. Compact, Creative, and Bold are available with a Job Search Pass.

Frequently asked questions

What should a loan officer resume show?

Identify lending type, relevant actual authorization and responsibilities. Give supported production or credit-work evidence with units, stages and periods, plus real systems and qualifications.

Does every loan officer need the same mortgage license?

No. Requirements depend on activities, employer, jurisdiction and applicable exceptions. Check the regulator and employer rather than deciding from the title alone.

Is an NMLS identifier the same as an active license?

No. Report actual license or registration and current status accurately. A number, test pass or submitted application alone does not establish permission for every activity.

How should I show production?

Separate funded principal, loan count, applications, commissions and revenue, and give a period. Tyler's fictional thirty-eight million dollars is funded loan value, not profit.

What if I am moving from processing or sales?

Show the tasks you actually performed and actual training or authorization status. Do not rewrite file support as independent origination or approval authority.

What should I check when changing mortgage employers?

Verify the new role's state licensing, registration, sponsorship and any applicable temporary-authority conditions. Oregon, for example, distinguishes an inactive license from accepted employer sponsorship.

Which tools should I list?

Name systems you actually used and the task supported. Familiarity with an underwriting engine does not itself grant final credit-approval authority.

How long should the resume be?

Follow application limits and use readable space for relevant lending evidence and status. Remove repetition before shrinking important context.

Do closing speed or pull-through prove clean files?

Not alone. Define the measure, period and population and describe separate quality checks when supported. Speed and conversion do not establish compliance or future default outcomes.

How do I edit this example?

Create a free account, choose Classic and replace Tyler's fictional work and license details. Save with Update, then inspect the PDF for correct units, current status and confidential information.

Build your loan officer resume now

Start from Tyler's example or a blank page. Free, a free account is required to edit, and the PDF has no watermark.

Build your resume, free
Loan officer resume example
Loan officer resume example The example above as an image, to save or share. To change it, use Edit & download this resume at the top of the page. Open the full-size image
Premium

More ways to make your CV yours

Unlock all three premium designs with a Job Search Pass. Your written content stays exactly as it is. Classic is always free.

Included with your pass

$12 once for 30 days

No subscription. Nothing renews. A 90-day pass is also available.

See Job Search Passes

Pass options open in a new tab. Your draft stays here.